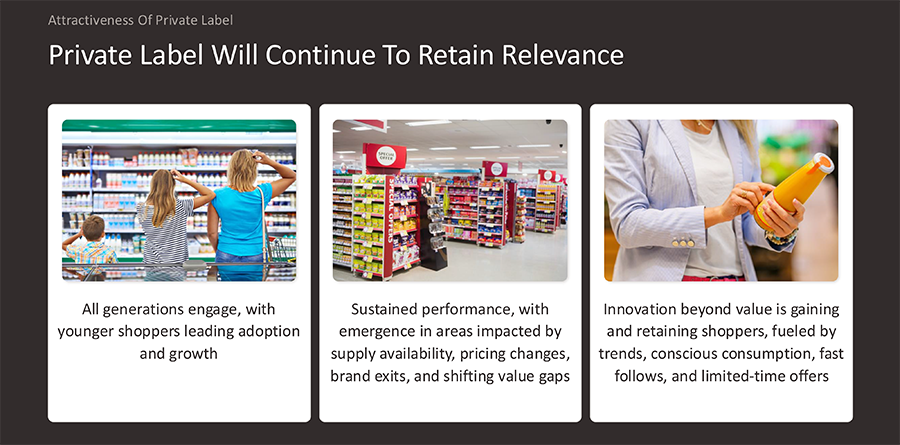
Private label dollar sales reached $251.3 billion for the 52 weeks ending June 14, up from $247.3 billion a year earlier, with growth driven more by shoppers buying store brands more often than by new households trying them, according to Chicago-based Spins.
The wellness-focused data company shared the findings during a recent webinar, “The Attractiveness of Private Label,” drawing on its Trilens panel data powered by Circana along with shopper surveys.
Trip frequency accounted for $3.7 billion of the year-over-year change and household penetration added $1.5 billion, while spending per trip declined $1.2 billion on lower units per trip and price per unit.
“This is an important shift because it suggests private label is becoming part of shoppers’ regular routines, rather than simply being a trade down option when prices are high,” said Emily Munz, distributor insights manager.
The ‘E’
Alex Overstreet, retail insights manager, framed private label’s broadening appeal through what he said some economists now call an “E-shaped economy,” a shift from the “K-shaped” model in which the rich get richer and the poor get poorer. 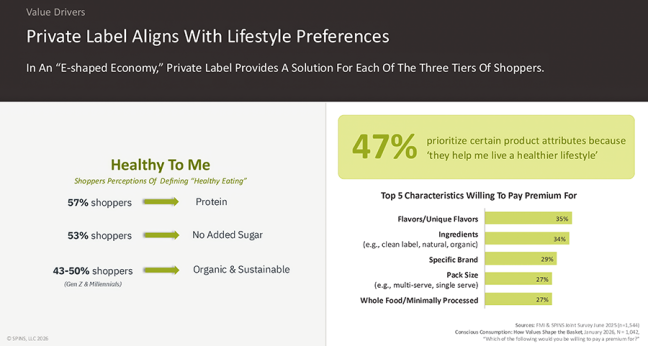
In the E-shaped view, upper-income shoppers at the top of the E buy store brands not for value but for product attributes such as more protein or no added sugar, while lower-income shoppers at the bottom buy for value. Among those shoppers, 60 percent are focused on price comparisons and 43 percent have decreased trips per store, he said.
The middle line of the E – a middle class that feels squeezed, Overstreet said – still prioritizes attributes such as organic or clean ingredients, creating an opening for premium private label.
“These consumers are shopping with intentionality and redefining premium to an attribute profile, not just a price point,” Overstreet said of shoppers in the middle and top tiers, pointing to offerings such as Walmart’s Bettergoods and Great Value lines and Kroger’s Simple Truth organic products.
“Premium private label creates a third rail for the shopper in-store outside of just value private label and national brand offerings.”
In cream cheese, for example, private label organic dollar growth accelerated to 89 percent over the last 12 weeks even as prices rose. And when one national retailer launched a premium private label cream cheese, SPINS saw an immediate on-shelf response from a conventional national brand that had been priced above $7, with all three tiers settling around $4 for an 8-ounce package.
Higher-income households on board
Adoption also is climbing fastest among higher-income households. In a January SPINS survey, 43 percent of shoppers earning at least $150,000 said they purchased more private label than in 2024, compared to 37 percent of those earning $75,000 or more and 25 percent of those earning less than $75,000.
Younger shoppers are leading the charge. Gen Z and Millennials contributed 81 percent of year-over-year private label dollar gains despite representing 17 percent of shoppers, with Gen Z private label spending up 31 percent versus a year ago.
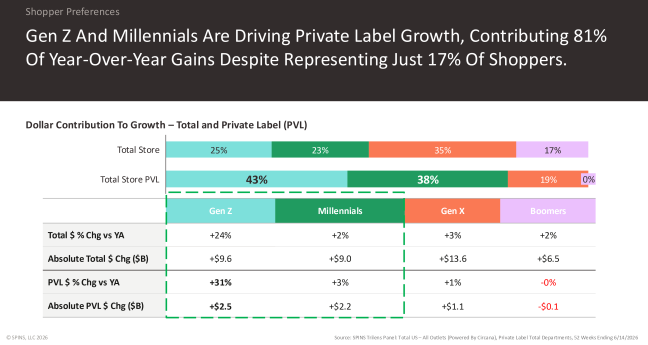 “Millennials and Gen Z are punching well above their weight when it comes to private label growth,” Munz said. “Private label is no longer just a value play. It is really becoming a mainstream choice and part of the shopper’s basket across many income levels and generations.”
Evonne Chan, senior market insights analyst, said the category has shed its old stigma.
“Now more than ever, I think private label has been seen as cool,” Chan said. “I don’t think anyone’s afraid to say that they shop private label anymore.”
Dollar share now 22 percent
Private label holds a 22 percent dollar share at $201 billion, with a two-year compound annual growth rate of 3.1 percent compared to 1.7 percent for national brands, according to Kyle Youngs, retail insights manager. He noted momentum has cooled, with dollar growth peaking at 6.1 percent in early 2025 before turning negative in the most recent 12-week period, with about 90 percent of those losses tied to refrigerated departments such as eggs, cheese, milk, alternative dairy and creamers.
Refrigerated fresh meat, poultry and seafood led private label dollar gains at more than $1.4 billion, with refrigerated beef accounting for nearly $1 billion, Youngs said.
Pricing has widened private label’s value gap. Private label’s average retail price rose 14 cents in two years to $3.86, while national brands climbed 20 cents to $5 – a difference of $1.14 – boosting private label’s value proposition 6 percent.
“I’m interested to see if the average retail price increases on private label creep back up to be more in line with the CPI food at home and the national brand increases, or if retailers continue to use private label as a lever to provide value to shoppers,” Youngs said.
Categories ripe for innovation
Norine Rudnicki, broker insights manager, said innovation opportunities lie in categories where young shoppers over-index but private label penetration remains low, including energy drinks, yogurt and frozen pizza.
“The next wave of private label growth may not come from categories where private label is already strong,” Rudnicki said. “It may come from categories where young shoppers are already showing enthusiasm, and retailers have more room to differentiate through product innovation, trends, premiumization and unique offerings.” 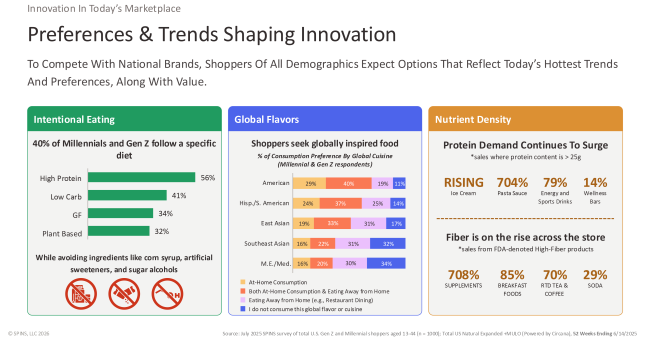
She cited retailers acting on shifting consumer values, with Aldi removing 44 ingredients from its private label portfolio, Walmart eliminating synthetic dyes across its private label food brands and Kroger debuting protein-focused offerings. Erewhon has built a private label vitamins and supplements line that accounts for nearly 30 percent of its VMS sales, compared to about 8 percent across the broader channel, and Sprouts launched a private label refrigerated cold brew in January, she said.
Limited-time offerings represent a lower-risk path, said Rudnicki, noting 76 percent of Trader Joe’s shoppers revisit the retailer, and Marks & Spencer launched more than 1,400 new items in 2025.
“Private label is just no longer a value play,” Rudnicki said. “It’s becoming a long-term growth driver because it appeals to a broad range of shoppers, continues to perform across changing market conditions and [is] increasing wins through innovation.”
Related: Report: Store Brands Hit 23.8% Unit Market Share As National Brands Lag